Risk Management
Factor Rx
SMA Factor RX Weekly Factor Review.
Purpose of the Factor Reports
At SMA Capital, we utilize a NON-ORTHOGONAL factor model to create the Factor RX suite of factors – which map risks that BARRA or Axioma might not capture.
The non-orthogonal approach allows us to develop sector specific factors pertinent to sector focused equity long/short strategies – HF positioning, crowding, multi-time period momentum or beta or correlations, retail activity etc.
What Makes Factor Rx Unique
Factor RX uses “dirty factors” where we intentionally use a non-orthogonal lens. The factors are seen as stand-alone “risks” within each market sector - ignoring the correlations with other factors in the market.
While they are not mathematically “pure” - they reflect the actual complexity and nuance of the market and risks specific to equity long/short strategies and provide greater granularity than standard quantitative market factors.
How to Read the Factor Charts
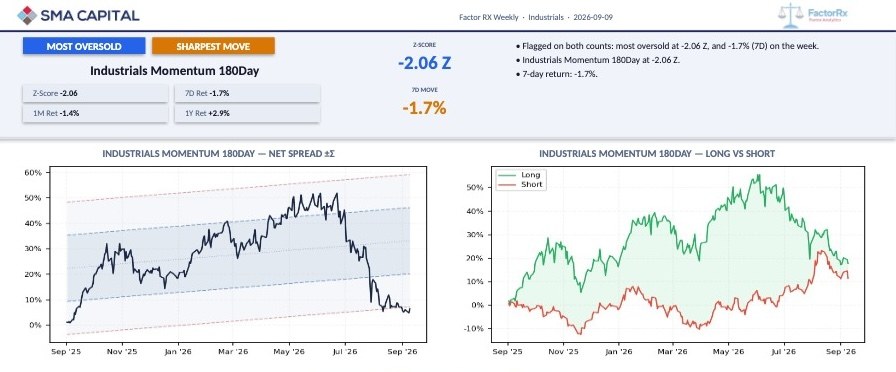
Each week, we highlight the biggest factor movers in each sector which we map for absolute return and z-score against a 1-year trend.
We focus on delivering insight about drivers of return and overbought or oversold risks which portfolio managers can monetize.
What to Expect Next From Factor Rx
Factor Rx risk dashboard is now available so you can view your portfolio through the Factor Rx lens.
This means you can track your portfolio exposures relative to the Factor Rx analysis and take action if portfolio exposures lead to unintended risks or missed opportunities relative to the recent factor performance.